 By Ishmael Junourgh
“Hello, have you received the money?”
“Yes, I have received it.”
“How much did you send?”
“I sent GH₵500, and they have sent me GH₵5,000.”
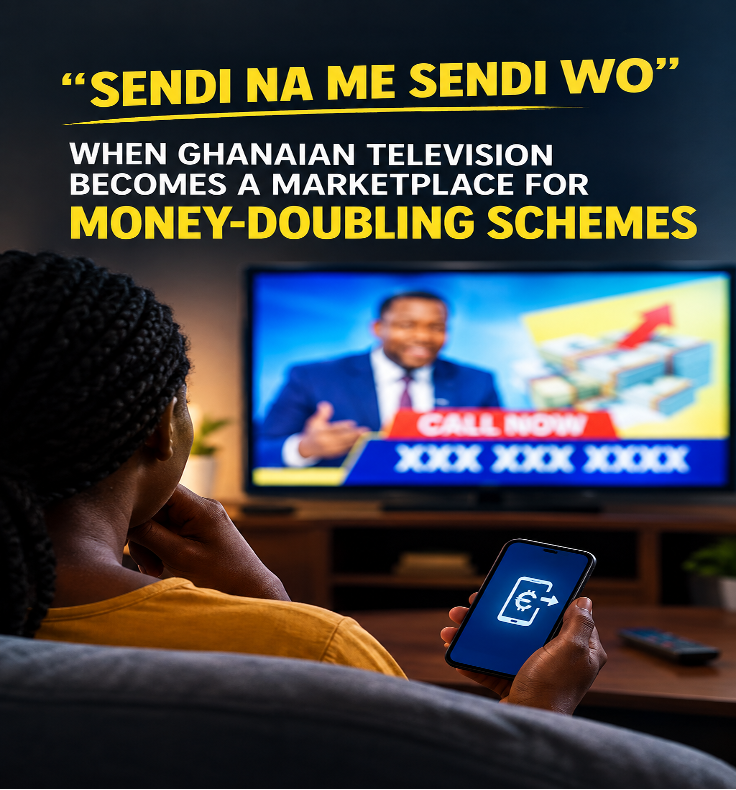
A presenter could sit comfortably in a studio, speaking with the confidence of someone who knows exactly what he is selling, while telephone numbers remain boldly displayed on the screen for viewers who may be interested in the opportunity being advertised. Then comes the part that makes the promise sound almost too real to question. A caller is put through, and after the usual greetings, the presenter asks whether the money has arrived. The caller answers in the affirmative, explains how much was sent and how much has supposedly been received in return, and several voices follow with similar stories. One person says he sent GH¢200 and received GH¢2,000. Another says she sent GH¢500 and got GH¢5,000. The programme continues, the calls continue, the testimonies continue, and somewhere another viewer begins to believe that perhaps this time there really is a way to turn a small amount of money into something much bigger within minutes.
That viewer may have spent the entire morning thinking about school fees, rent, food, hospital bills, a debt or a small business that desperately needs capital, and although the promise sounds extraordinary, the repeated success stories slowly begin to make it feel less extraordinary because people naturally become more willing to believe something when they hear others claiming to have already benefited from it. The television screen becomes the bridge between the promise and the viewer’s confidence, and after watching one caller after another apparently confirm that the money works, the viewer takes out the savings that were supposed to carry the family through the month, opens a mobile money wallet, dials the number on the screen and sends the money.
The programme is still running.
The presenter is still talking.
But the viewer has now moved from watching the promise to becoming part of it.
What happens afterwards is where the real story begins.
At first, there may be nothing to suggest that anything has gone wrong. The victim waits for the promised return, perhaps expecting the money within five minutes because that is what was said on television, and when nothing arrives, the first call may be answered with a simple explanation about network problems, transaction delays or a technical issue. The victim is told to wait a little longer, and because the programme looked organised and because other people appeared to have received their money, waiting seems reasonable.
Then another condition may appear.
Perhaps the victim is told that an additional payment is required before the transaction can be completed, or that a processing charge, activation fee, tax, clearance payment or some other unexpected amount must be sent before the promised money can be released. The victim, already afraid of losing the money that has gone in, may send the additional amount because at that moment the mind is no longer asking whether the original promise was believable; it is asking how to recover what has already been invested.
Then the waiting begins again and again,
Eventually, the people who sounded so accessible when they were asking the public to send money may stop answering altogether, and in some cases the telephone number may no longer connect or the victim may find that communication has simply disappeared. The television programme, meanwhile, may continue as though nothing has happened, with another presenter speaking to another caller and another viewer somewhere else beginning the same journey.
This is how a promise made through a television screen can end with a person sitting beside an empty mobile-money balance, wondering how money that took months to save could disappear in a matter of minutes.
One of the most disturbing elements of money-doubling schemes is not simply the promise that money can multiply quickly, but the way the promise is presented as though it has already been tested successfully by ordinary people.
A person who hears a stranger say, “I sent the money and I received it,” is being offered more than an advertisement. He is being offered what appears to be evidence. The viewer is no longer being asked merely to trust the presenter or the people behind the scheme; he is being invited to trust another member of the public who supposedly took the same risk and lived to tell the story.
In 2020, the police publicly warned about television money-doubling schemes and specifically addressed the use of supposed beneficiaries as part of the deception. ACP Dr Gustav Herbert Yankson, then Director of the Cyber Crime Unit of the Criminal Investigations Department, said people were being deceived through false testimonies from individuals who claimed to have benefited from the schemes, adding that the testimonies were fake and were being used to deceive the public. Police also said they had received numerous complaints from victims who had sent money and waited in vain for the promised returns.
That revelation deserves more attention than it often receives.
The problem begins when the credibility of television is used to make questionable promises appear trustworthy.
Most viewers do not have the time, expertise or access to independently investigate every advertisement they encounter. When a financial opportunity appears on television, particularly one presented repeatedly and surrounded by apparently successful callers, many viewers will naturally assume that somebody somewhere has checked the company, the people behind it and the legality of what is being offered.
That assumption can become dangerous when the underlying scheme has not been properly verified.
The public is often told to be careful, to verify investment companies, to avoid unrealistic promises and to report suspicious schemes, and all of that advice is necessary, but there is something deeply unsatisfactory about repeatedly warning ordinary citizens to protect themselves from a danger that regulators have already identified while the channels through which that danger reaches them continue operating. A television viewer does not have the investigative capacity of the Securities and Exchange Commission, the regulatory authority of the National Communications Authority or the monitoring structures available to the National Media Commission, so it is reasonable to ask why the burden of protection should fall so heavily on the individual viewer after the authorities have already identified the problem.
The issue becomes even more difficult to ignore when the evidence shows that this is not a new discovery.
The SEC’s 2023 annual report said its media monitoring unit had identified 33 satellite television stations advertising suspected investment schemes, loan schemes and money-doubling activities, and that the National Media Commission had formally warned the owners of those stations to stop advertising fraudulent investment schemes or face sanctions.
Then, in November 2025, the SEC again issued a public warning about suspected fraudulent investment schemes being advertised on television and identified 33 television channels associated with such advertisements, stating that the schemes had not been approved, authorised or licensed by the Commission.
If the same problem can be identified in 2023 and publicly warned about again in 2025, the obvious question is no longer whether regulators know about it.
The question is what happens after the warning.
What sanctions were actually imposed? Which stations were suspended, fined or otherwise disciplined? How many advertisements were removed?
How many stations were ordered to provide evidence that they had stopped carrying such promotions?
These are not questions being asked to attack television broadcasters as a whole, because Ghana’s television industry performs an important public function and many stations work responsibly within the law. They are questions about whether the country’s enforcement system is strong enough to make regulatory warnings mean something beyond the paper on which they are printed.
Government’s responsibility is to build and enforce systems that make it increasingly difficult for dishonest people to use powerful public platforms to reach vulnerable citizens, collect their money and disappear.
And if those systems already exist, then the public is entitled to ask a very simple question: why are we still having the same conversation?